Millions of Americans who receive Social Security benefits are waiting for the next cost-of-living adjustment (COLA). The annual increase is designed to help retirees, people with disabilities and eligible survivors keep up with rising living costs.
The final inflation report needed for the 2027 adjustment is scheduled for October 14, 2026, according to the U.S. Bureau of Labor Statistics. Until the relevant data is released and the Social Security Administration announces its decision, the next increase remains an estimate rather than a confirmed figure.
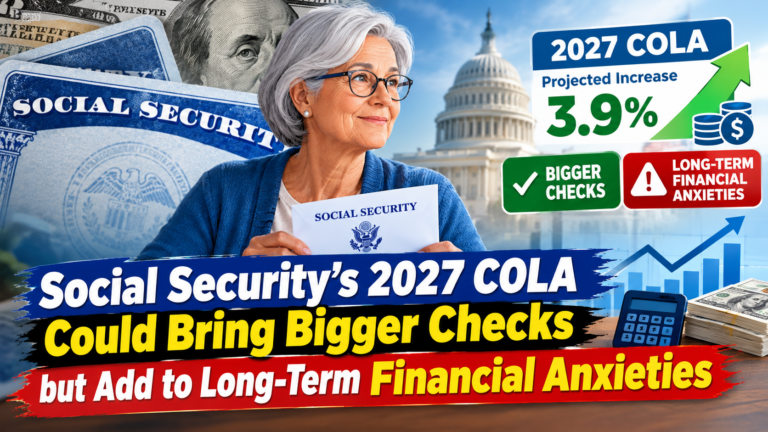
Some early projections suggest that beneficiaries could receive a 3.5% increase in 2027. That would be a expressive boost to monthly expenses. However, the same inflation pressures that lead to larger benefit adjustments can also create financial challenges for households and put additional pressure on Social Security’s long-term finances.
When Will Social Security Declare the 2027 COLA?
The Social Security Administration typically announces the annual COLA in October after the necessary inflation data becomes available.
The modification is based on changes in the Buyer Price Index for Urban Wage Payees and Clerical Staffs, normally known as the CPI-W. The calculation compares average inflation during the third quarter of the current year with the same period in the previous year.
The September 2026 Consumer Price Index report is scheduled for release on October 14 at 8:30 a.m. Eastern Time. This report will provide the final monthly inflation data needed for the 2027 calculation.
Beneficiaries should wait for the official announcement before making financial decisions based on a specific percentage. Forecasts can change as new inflation figures become available.
Why a Upper COLA Could Be on the Method
Social Security benefits have generally received annual cost-of-living adjustments since the current system began using automatic COLAs in 1975. These increases are intended to help benefits maintain their purchasing power as prices rise.
Several economic pressures have contributed to concerns about inflation in 2026. Trade policies and tariffs can increase the cost of imported products and materials. Businesses may pass some of those other expenses on to customers, even though the result varies across industries and goods.
Energy prices are another important factor. Oil supply disruptions and tensions involving Iran and the wider Middle East can affect global fuel markets. When gasoline, diesel and transportation costs increase, businesses may face higher expenses for moving goods and providing services.
However, inflation has multiple causes, including changes in consumer demand, supply conditions, wages and global commodity prices. It would be inaccurate to attribute every increase in consumer prices to one government policy or a single international event.
For Social Security recipients, the practical concern is how these rising costs affect everyday expenses such as food, housing, utilities, transportation and healthcare.
What a 3.5% Social Security Increase Could Mean
The Senior Citizens League and Social Security policy analyst Mary Johnson have been cited among those projecting a possible 3.5% COLA for 2027. This figure is an estimate, not the official adjustment.
If the final increase were 3.5%, the additional monthly payment would depend on a person’s current benefit amount.
For instance, someone getting $2,000 per month would see an growth of around $70, bringing the monthly payment to $2,070 before any other amendments. A beneficiary receiving $2,500 would receive about $87.50 more per month, for a new monthly amount of $2,587.50.
These examples illustrate how the percentage would work. They do not represent confirmed 2027 benefit amounts.
A advanced payment can help families manage expanding expenses. Yet the growth does not automatically mean receivers will have more money missing above each month. If rent, groceries, insurance premiums and medical expenses rise faster than their income, much of the adjustment may be absorbed by those costs.
Why Rising Increase Can Be Hard for Retirees
COLAs are intended to protect Social Security benefits against inflation, but they do not guarantee that every beneficiary will maintain the same standard of living.
Older Americans have different spending patterns from the general population. Some devote a substantial share of their income to housing, prescription medicines, health insurance and other essential services. Prices in these categories may not move in line with the inflation measure used to calculate the COLA.
Healthcare expenses can be particularly challenging for people living on a fixed income. Medicare premiums and other out-of-pocket costs may also affect how much of a benefit increase remains available for everyday spending.
This means a larger COLA can provide welcome relief without fully solving the financial difficulties many retirees face.
Beneficiaries should review their monthly budgets and consider how changes in essential expenses could affect their finances. Any planning should use official benefit amounts and current expense information rather than relying solely on preliminary COLA forecasts.
Social Security’s Long-Term Funding Challenge
The debate over the 2027 COLA comes as Social Security continues to face a long-term funding challenge.
The Social Security Board of Trustees evaluates the program’s expected income, benefit payments and financial reserves over a 75-year period. Its projections account for factors such as wages, employment, population trends, life expectancy and future benefit costs.
The 2026 Trustees Report projects that the Old-Age and Survivors Insurance (OASI) trust fund reserves will be depleted in the fourth quarter of 2032. If that happens without legislative changes, continuing income would cover approximately 78% of scheduled benefits at that time.
This does not mean Social Security would suddenly stop operating. Payroll taxes and other dedicated income would continue to support payments. However, without changes to the program, the money coming in would not be sufficient to pay all scheduled retirement and survivor benefits in full.
The Trustees also project a longer-term financial shortfall. Addressing that challenge could require lawmakers to consider a combination of revenue changes, benefit adjustments or other reforms.
Could a Larger COLA Put More Pressure on the Trust Fund?
A cost-of-living adjustment raises the amount paid to eligible beneficiaries. When benefits increase, the program’s total scheduled payments can also rise.
If inflation remains elevated over an extended period, future COLAs may be larger than they would be under a lower-inflation environment. That can increase projected benefit costs and affect the program’s financial outlook.
However, the relationship is not as simple as saying that one large COLA will cause Social Security’s reserves to run out sooner. The program’s financial projections depend on several economic and demographic assumptions, including payroll tax revenue, employment, wages, mortality and future inflation.
A 3.5% COLA would not, by itself, establish a new trust fund depletion date. That date would depend on the combined effect of many variables and any changes enacted by Congress.
The key issue is that higher benefits can help recipients cope with inflation while also increasing scheduled payments. Policymakers must consider both effects when evaluating the program’s long-term financial condition.
What Beneficiaries Should Watch Next
The next important development is the release of the September inflation report on October 14, followed by the Social Security Administration’s official COLA announcement.
Until then, beneficiaries should treat estimates as provisional. A projected 3.5% increase may be useful for preliminary budgeting, but it should not be mistaken for a guaranteed payment change.
It is also important to distinguish between the annual COLA and the program’s long-term funding outlook. The COLA determines how eligible benefits are adjusted for inflation. Trust fund projections assess whether the program’s expected income and reserves will be enough to cover scheduled payments in future years.
Both issues matter to retirees, but they answer different questions.
The Bottom Line
Social Security recipients could receive a larger monthly benefit increase in 2027 if current COLA estimates prove accurate. That additional income may help offset rising prices, especially for households that rely heavily on retirement benefits.
At the same time, persistent inflation can leave retirees struggling to keep up with essential expenses, even when their monthly checks increase. Social Security’s long-term funding challenge also remains unresolved, with the latest Trustees Report projecting that OASI reserves will be depleted in late 2032 unless changes are made.
For now, beneficiaries should wait for the official 2027 COLA announcement, keep track of their household expenses and follow developments in Social Security funding. The final adjustment will determine how much benefits rise, while future policy decisions will shape the program’s ability to pay scheduled benefits over the long term.
About The Author